Western Union Send Money Now

Screenshots
Details
- Rating
- 151.79K reviews
- Version
- 16.4
- Developer
- Western Union Apps
Analysis by Norviv
Sending money across borders is one of those jobs where convenience matters, but confidence matters more. I spent time looking at Western Union Send Money Now as a finance app rather than treating it like a simple shortcut to a transfer website. My impression is that it is built for people who want to arrange an international remittance from a phone, keep the process in one place, and return to a familiar service when another person is waiting for the funds.
The app comes from Western Union Apps and is free to install. It has been available since Aug 18, 2011, which gives it a much longer history than many newer mobile finance tools. Its store category is Finance, and its Everyone age rating makes the presentation broadly accessible. That does not mean every transfer is equally suitable for every user; the important questions are where the money is going, how quickly it needs to arrive, and whether the recipient needs a bank deposit, cash collection, or another available delivery route.
What I like most is the clear purpose. This is not a budgeting dashboard, an investing platform, or a general-purpose wallet trying to do everything. It focuses on international money transfers and remittances. That narrow role makes it easier to judge: if you regularly support family abroad, pay someone in another country, or need a recognizable transfer service while traveling, the app has a sensible place in your toolkit. If you only move money between your own local accounts, it is probably more than you need.
How the app feels when speed matters
I find that speed in a money-transfer app is really about avoiding uncertainty, not simply moving through screens quickly. This section looks at how a focused remittance workflow can help when someone needs support soon, while keeping the final review deliberate. That distinction matters most when an urgent request arrives and the next decision is how the recipient will collect the funds.
Starting a transfer without unnecessary detours
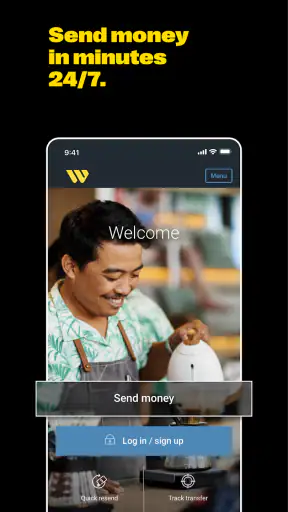
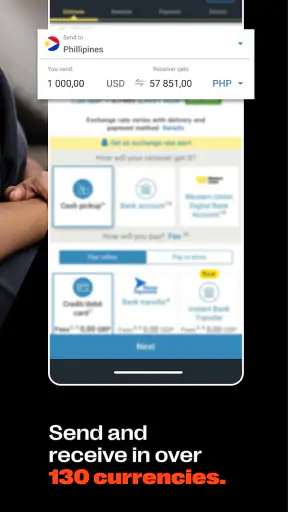
In my experience, the perceived speed of a money-transfer app begins before any payment is made. A useful app should help me understand the route, recipient, and amount without making me hunt through unrelated tools. Western Union Send Money Now benefits from its focused design: I open it with a specific task in mind rather than navigating through a large collection of financial products.
That focus is especially useful when I am sending a remittance under pressure. For example, imagine a family member abroad needing help with a bill and messaging me while I am commuting home. I would rather begin the transfer from a dedicated finance app than reconstruct the process from a browser bookmark, an old message, and several disconnected confirmation screens. The mobile format is most valuable here because the transfer can be started where the request arrives: on the phone I already carry.
Still, I would not confuse a quick app experience with instant delivery. The app can make the sending process feel direct, but the final timing depends on the selected destination and delivery method. A transfer intended for urgent cash collection should be considered differently from one headed to a bank account. Before pressing the final confirmation, I recommend checking the recipient details, destination, delivery option, and total amount carefully. Correcting a mistake after sending is far more frustrating than spending another minute reviewing it.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
Where the speed advantage is most noticeable
The strongest speed advantage is repeat use. Once I know the recipient and understand the route I normally use, the app becomes a practical launching point for another remittance. That is a different benefit from raw transfer speed: it reduces the time I spend remembering the steps. Someone who sends money to the same relative every month may appreciate this more than someone making a single unfamiliar transfer.
There is also a useful distinction between comparing the app with a bank branch and comparing it with a competing transfer service. Against a branch visit, a phone-based workflow is naturally more convenient. Against other digital remittance services, the decision is less simple. A competitor may suit a particular corridor, funding method, or recipient preference better. I would compare the final amount received and the delivery choice, not just which app opens fastest.
My practical speed tip is to prepare before urgency arrives. Keep the recipient’s name and destination details available, know whether the person expects a bank deposit or cash pickup, and avoid beginning the process with a weak connection or a nearly empty phone. These small steps do more for a smooth transfer than repeatedly reopening the app and hoping the process will move faster.
Heavy-use moments, stability, and recovery
When I use a finance app repeatedly, interruptions and busy moments make clear recovery habits as important as the initial transfer flow. Here I consider how I would handle a paused session, coordinate with the recipient, and avoid acting twice when the outcome is unclear. Those practical habits lead naturally to a closer look at what the phone itself needs for dependable everyday use.
Using it during busy personal situations
Finance apps are often used at inconvenient times: during a lunch break, in an airport, after receiving a worried message, or while coordinating help with relatives in another time zone. Western Union Send Money Now fits that kind of use because its purpose is easy to remember. I do not need to decide which part of the app handles a remittance; the entire experience is centered on sending money.
Heavy use does not necessarily mean making many transfers in a row. It can mean repeatedly checking a transfer, reviewing details, or returning to the app while coordinating with the recipient. In those moments, I value a stable, understandable flow more than decorative extras. A finance app should make me feel that I know what I am confirming. The Western Union identity also helps with recognition: I am not wondering whether I opened an unrelated tool with a similar name.
However, the app is not a replacement for careful communication. The recipient should know which delivery method to expect, and both sides should agree on the spelling of important personal details. A transfer can be technically easy to start and still become inconvenient if the recipient arrives at the wrong collection point or expects funds through a different route. I consider this a key trade-off: the app simplifies the sender’s side, but it cannot remove the need to coordinate the receiving side.
What to do when the process is interrupted
Phone use introduces ordinary interruptions. A call can arrive, the screen can lock, the connection can change, or the app can be closed before I finish. My safest habit is to avoid assuming that an interrupted screen means a transfer was completed. I would reopen the app, review the current status, and check any confirmation information before trying again. Sending a second time simply because the first screen disappeared is an avoidable risk.
This recovery approach is particularly important when a user is working quickly. Write down or securely retain the relevant confirmation details when the transfer is complete, then share only the information the recipient actually needs. Do not send sensitive account or identity details casually through a group chat. The app’s convenience should be paired with basic discipline, especially when money is involved.
For users who make transfers regularly, I suggest creating a small personal checklist outside the app: recipient spelling, destination country, delivery method, amount, and final confirmation. That may sound old-fashioned, but it is a useful safeguard when several relatives have similar names or when I am sending money while distracted. The checklist also makes recovery easier because I can tell whether I was still preparing the transfer or had already confirmed it.
Reliability is more than staying open
When I judge reliability, I look beyond whether an app launches. A trustworthy remittance tool needs to support a clear understanding of what I am doing, help me avoid duplicate actions, and leave me with enough information to follow up if something does not go as expected. Western Union Send Money Now has the advantage of belonging to an established transfer brand, and that familiarity can be reassuring for people who do not want to experiment with an unknown service for an important family payment.
At the same time, brand recognition should not replace checking the transaction itself. I would still verify the recipient, destination, delivery option, and amount every time. A stable app cannot protect me from a wrong name or an incorrect destination entered during a rushed session. This is one area where the human workflow matters as much as the software.
The app has a 4.7 average from around 348 thousand ratings, with roughly 152 thousand written reviews, and it has passed 10 million installs. Those figures suggest broad adoption and a large body of user experience around it, but I would interpret them as context rather than a promise that every transfer will feel identical. A finance app can be well regarded while individual results still depend on the route and the user’s circumstances.
Device limits and day-to-day practicality
A mobile remittance tool is only practical if the device can run it and I can use it comfortably when needed. This section covers the operating-system threshold, routine preparation, and the situations where a phone-based transfer is more useful than a branch or another service. I also weigh when keeping a dedicated app installed is worthwhile for someone who sends money only occasionally.
Older phones can still be part of the decision
The current version is 16.4, and the app requires Android 8.0 or later. That is a useful detail for anyone keeping an older phone in service, using a backup handset, or helping a relative who does not upgrade frequently. Before planning an urgent transfer, I would check the phone’s operating system and make sure the app can be installed and updated normally.
On a compatible device, I would expect the main practical demands to be modest compared with games, video editors, or other visually intensive apps. This is a focused finance application, so its value is in completing a transaction rather than rendering elaborate content. Even so, I would avoid making assumptions about performance on every phone. Available storage, operating-system condition, connection quality, and background activity can all affect how comfortable a mobile session feels.
A low battery is a more serious problem than a slightly slower screen. If I am sending money while traveling, I would charge the phone first and keep a reliable connection available. Losing access halfway through a financial task is not merely inconvenient; it makes it harder to know what happened. A prepared device is part of a reliable transfer workflow.
Who benefits from the mobile format
The app makes the most sense for people who send remittances from different places: home, work, or while traveling. It is also useful for users who prefer a recognized mobile service over visiting a physical location. Someone supporting relatives abroad may value the ability to begin a transfer without arranging a trip to a branch, especially when the recipient’s needs do not fit a predictable schedule.
It is less compelling for a person who sends money only once and already has a cheaper, familiar method that the recipient prefers. It may also be the wrong choice for someone whose main requirement is detailed household budgeting, bill tracking, or local peer-to-peer payments. Those tasks call for different tools. Western Union Send Money Now is strongest when the central problem is moving money internationally through a known remittance service.
Another trade-off concerns comparison shopping. The free installation is helpful, but the app itself should not be judged only by the absence of an upfront price. For each transfer, I would compare the total cost and the amount the recipient receives with the usual alternatives available for that specific route. A bank, another remittance app, or a local transfer service may be better in one situation and worse in another. The right comparison is the complete transaction, not the download price.
Small habits that improve the experience
I would use the app in a calm setting for the first transfer rather than learning it during an emergency. That gives me time to understand the recipient flow and delivery choices. For later transfers, I would still pause at the final review instead of treating a familiar recipient as automatically correct. Familiarity is helpful, but it can also encourage careless tapping.
I would also separate planning from confirmation. First decide how much the recipient needs and how they will receive it. Then open the app and enter the details. This avoids changing the amount or delivery method impulsively because a screen presents several choices. It is a simple workflow improvement, but it makes the app feel more controlled and reduces the chance of an accidental selection.
Finally, I would keep the app updated when the phone allows it, particularly before a planned trip or a recurring remittance. The current version is 16.4, and staying current is a sensible maintenance habit for any finance app. I would not wait until a family emergency to discover that an older handset cannot run the version I need.
My performance verdict for remittance users
Western Union Send Money Now is a focused finance app that I would recommend to someone who regularly sends money internationally and wants a mobile-first way to arrange the transfer. Its perceived speed comes from reducing the distance between receiving a request and starting the process. Its reliability comes less from flashy features and more from a clear purpose, a familiar developer name, and a workflow designed around remittances.
It is not the universal best option. A local bank may be more convenient for domestic transfers, another service may offer a better overall deal on a particular route, and a branch may still be preferable for someone who wants in-person assistance. I would also skip it if my needs are mainly budgeting or everyday local payments. The app earns its place when the recipient is abroad and the delivery method matters.
For my own use, the deciding test would be practical: can I identify the recipient confidently, choose the right delivery route, review the final amount without rushing, and retain the confirmation afterward? If the answer is yes, the app offers a sensible balance of convenience and control. If I cannot answer those questions, no amount of perceived speed makes the transfer ready.
The broad adoption is encouraging, with more than 10 million installs, and the Everyone rating makes it approachable for a wide audience. But the best reason to choose it is not a number on a store page. It is the combination of a dedicated remittance purpose, a mobile workflow, and the recognition of Western Union Apps behind it. For international sending, I see it as a practical tool rather than a complete financial home—useful when its specific job matches yours, and worth comparing carefully whenever cost, delivery speed, or recipient convenience is the priority.
Frequently Asked Questions
01What is Western Union Send Money Now, and how does it work?
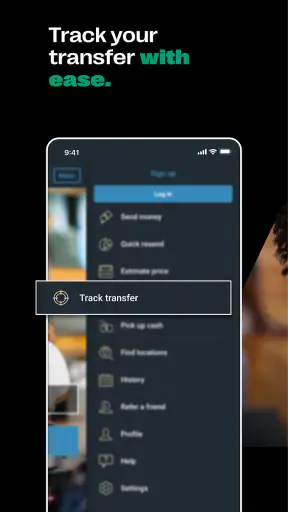
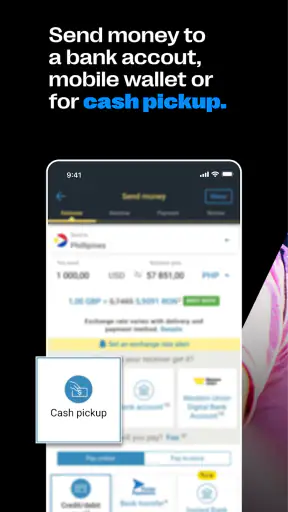
Western Union Send Money Now is a mobile service for sending money to people in other countries or within your own country. After creating an account, you enter the recipient’s details, choose a delivery method such as bank deposit, cash pickup, or mobile wallet where available, and pay for the transfer. The app then provides a tracking number so you can follow the transaction’s progress.
02How much does it cost to send money with Western Union Send Money Now?
Transfer costs are not fixed and may depend on the destination, amount, payment method, delivery option, and current exchange rate. Before confirming a transaction, the app normally displays the transfer fee, the exchange rate, and the exact amount the recipient should receive. It is worth comparing these details carefully, because card payments or faster delivery options may cost more than other choices.
03How long does a Western Union money transfer take?
Delivery time varies according to the selected service and destination. Cash pickup can sometimes be available within minutes, while bank deposits and mobile wallet transfers may take longer because they depend on local banking systems and verification procedures. Weekends, holidays, compliance checks, incorrect recipient information, and payment processing delays can also affect the estimated arrival time shown in the app.
04What information is required to send money through the app?
You generally need to provide your personal information, a valid payment method, and accurate details about the recipient. Depending on the country and transfer amount, Western Union may request identity verification or additional documentation. For cash pickup, the recipient’s name must usually match their official identification exactly. Reviewing every spelling, account number, and destination detail before payment can help prevent delays.
05Is Western Union Send Money Now safe, and how can I avoid scams?
The app uses account security measures and transaction tracking, but users should still remain cautious because scammers often misuse legitimate money-transfer services. Never send money to someone you have not independently verified, and do not share passwords, verification codes, or transfer details with strangers. Be especially careful with urgent requests, fake prizes, romance scams, and sellers who insist on Western Union as the only payment method.


